The first Making Tax Digital deadline passed on 7 August, and the numbers tell their own story.
HMRC estimated that around 864,000 sole traders and landlords would need to join the system when it became mandatory in April. By 12 August, just over 570,000 had signed up. Of those, 436,000 had filed the first quarterly update on time. That leaves close to 294,000 people who are legally within the regime and have not registered at all.
HMRC's response is to stop waiting. From September, it has begun automatically signing up taxpayers it believes should already be using Making Tax Digital for Income Tax, working through them in stages over the coming months. Letters are landing now.
What the letter means
Anyone who receives one should read it rather than file it. Being enrolled by HMRC does not fix anything on its own. It creates an obligation without creating the means to meet it.
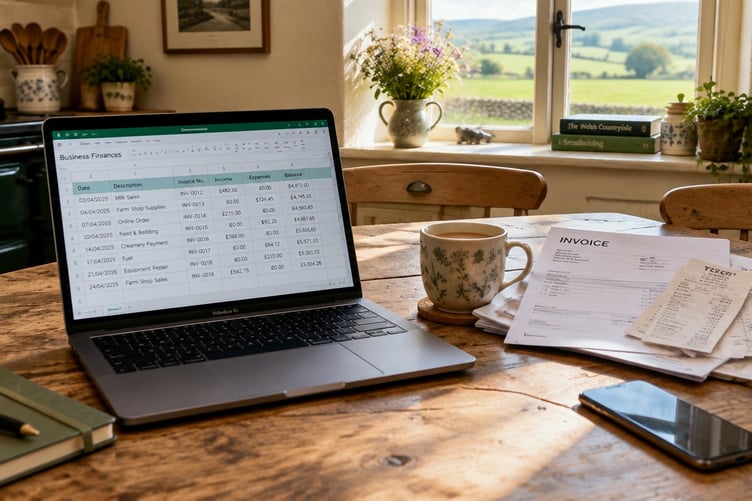
The requirement is to keep digital records and to send a quarterly summary of income and expenses through HMRC-recognised software. Automatic enrollment does not supply the software, set up the records or make the submission. Someone still has to do that.
There is also a reasonable chance the letter is wrong. HMRC is working from 2024/25 tax returns, so anyone whose circumstances have changed since a property was sold, a business was wound down, or income dropped below the threshold may be enrolled on out-of-date information. That is worth checking rather than accepting.
The next deadline is 7 November
For anyone who missed August, the position is more forgiving than it looks. Quarterly updates are cumulative. The second update, due 7 November, covers everything from 6 April onwards, so filing it on time brings both quarters up to date in one go.
HMRC has also confirmed there will be no penalty points for late quarterly updates during 2026/27. That is a deliberate first-year easement, and it should not be mistaken for a wider amnesty. Penalties for late tax returns and late payments apply exactly as before. The Self Assessment deadline is still 31 January, and quarterly updates do not replace the annual return. They sit alongside it, and all four must be submitted before the return can be filed.
The easement ends with the tax year. From 6 April 2027, a points-based system applies: one point for each missed quarterly deadline, and a £200 fixed penalty once four points have accumulated.
Why April 2027 matters more here than April 2026 did
From April 2027, the threshold drops from £50,000 of qualifying income to £30,000. That single change pulls in a far larger group, and it lands disproportionately on this part of Wales.
Self-employment has always run higher in mid and west Wales than almost anywhere else in the country. Research published by Business News Wales put the figure at around one in four working people in Powys and Ceredigion, and one in five in Gwynedd and Pembrokeshire, against roughly one in eight across Wales as a whole. Cardiff University found that self-employed people in Wales are three times more likely to work in agriculture than the UK average, and that more than 97% of them employ nobody at all.
That is the profile the £30,000 threshold captures. Farms, holiday lets, campsites, trades, freelancers and one-person businesses with turnover that clears £30,000 comfortably but leaves no room for a finance function. Qualifying income is gross, not profit, which catches out people who assume their margins keep them clear of it. Someone with a smallholding and a couple of cottages may be well under £30,000 in taxable profit and well over it in qualifying income.
Digital exclusion is a real exemption
Exemptions exist, and one of them is directly relevant to this area. Anyone who cannot reasonably use digital tools, whether through age, disability, location or lack of reliable connectivity, can apply to be exempted.
In a region where broadband and mobile coverage remain patchy in places, that is not a technicality. It is a genuine route for people who would otherwise be required to file quarterly from a farmhouse with no usable connection. Applications take time to process, which is an argument for looking at it well before April 2027 rather than after.
The practical position
The people most exposed are not those who have decided to ignore Making Tax Digital. They are the ones who have not yet realised it applies to them, or who assume the annual accountant visit in January will sort it out as it always has. That assumption stopped being true in April.
Anyone above £50,000 should check that they are registered and get the November update in. Anyone between £30,000 and £50,000 has about seven months, which sounds generous and will not feel generous once the software has to be chosen, the records set up, and a year's habits changed.
"We are still having conversations with business owners who are not sure if they are within the scope of MTD, including sole owners of limited companies. We are still also having to explain that MTD does not mean sole traders have to submit full self-assessments and pay income tax four times per year,” said Rhys Evans, dDirector at RNE Accounting, which works with sole traders, landlords and small businesses across Wales.
“My advice for anyone who is expecting to fall within the scope of MTD from next April is to get prepared sooner rather than later. Make sure your software is compliant, your bank feed is connected, and importantly, your process for capturing digital copies of invoices and receipts is up and running. If any of this is concerning you, speak to your accountant early."
Find out more about RNE Accounting here.
Comments
This article has no comments yet. Be the first to leave a comment.