A petition calling for holiday lets to lose tax relief which can leave some owners paying neither council tax nor business rates has been referred to a Senedd committee.
The petition, which closed on 2 November and was referred to the Petitions Committee on 4 November, argues that houses and flats used as holiday accommodation should pay council tax regardless of how often they are let.
It attracted 340 signatures, exceeding the 250 needed for committee consideration.
The campaigner behind it claims more than 10,000 holiday lets across Wales paid neither council tax nor business rates in 2024, estimating this represented approximately £48 million in potential council tax revenue.
Those figures are the petitioner's estimates, based on information obtained from local authorities, rather than a new official assessment of tax receipts.
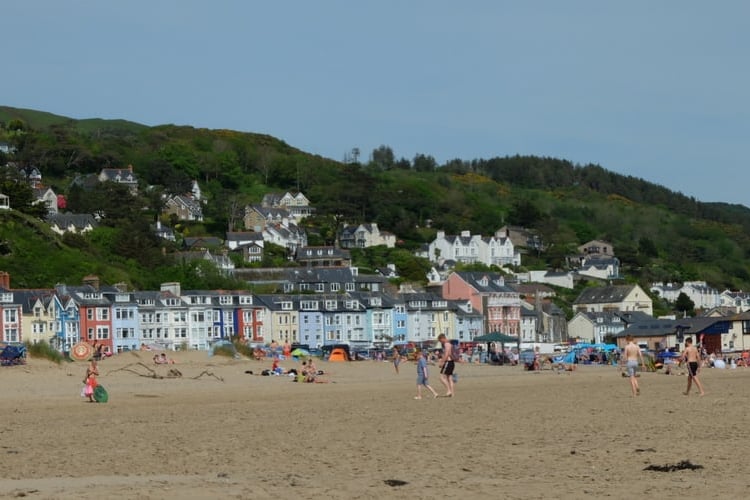
The issue is particularly relevant in Ceredigion, where tourism accommodation and second homes have long been part of the debate surrounding housing availability and council finances.
Ceredigion County Council imposes a 150 percent council tax premium on second homes, meaning properties subject to the premium face bills equivalent to 250 percent of the standard rate.
However, holiday lets meeting Welsh Government criteria can instead be classified as businesses and become liable for non-domestic rates.
Generally, properties must be available for letting for at least 252 days annually and actually let for 182 days, although rules introduced in April allow certain operators to use averages across several years.
Eligible properties with rateable values of £6,000 or less can receive full small business rates relief, potentially reducing their bills to zero.

The petition calls for this arrangement to change, arguing that residential properties should contribute through council tax regardless of their holiday-let status.
However, its referral does not mean the Senedd or Welsh Government has agreed to amend the rules. Committee members will now consider what action, if any, should follow.
Comments
We've recently changed our login process. If you have an account for commenting, you will need to re-register on the login window.
This article has no comments yet. Be the first to leave a comment.